By ACP Tax Advisory | Published on October 20, 2026 | Last updated October 20, 2026
If you are wondering what you can still do about your 2026 taxes, the answer is more than many business owners expect. This year-end tax checklist covers what to review, what to collect and what to decide before December 31, and most items are quick to check.
A common assumption is that taxes are an April matter, something to sort out when your tax advisor asks for documents. By April, though, the year is already closed, since the purchases are made, the contractors are paid, and the estimated payments were either sent or skipped. What remains is reporting what happened, which is why the months before December 31 are the ones that still let you shape the result.
Timing matters for cash, too. More than half of small employer businesses said in 2024 that paying operating expenses was a challenge, and a similar share reported uneven cash flow, so a tax bill can land on a budget that is already tight. A year-end tax checklist gives you time to plan for it.
Why a year-end tax checklist matters before April
Many small businesses use a calendar tax year, which means 2026 closes on December 31. In general, what counts for 2026 is what happened inside that year, so a purchase, a payment or a correction made in December can still affect this year’s return, while the same step taken in January belongs to 2027, which is why a year-end tax checklist works best while those steps are still available. The details depend on your entity type and how your business accounts for income and expenses, which is one reason some items on this list call for an individual look.
A year-end tax checklist covers the records as much as the decisions, since most of what your tax advisor will ask for in January already exists in December.
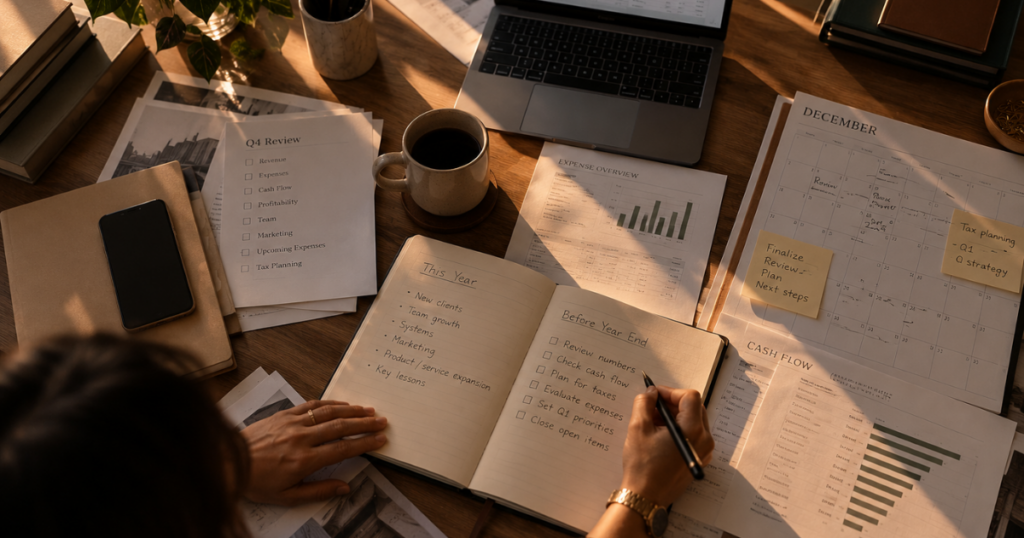
Do you know your profit, not only your sales?
Consider a hypothetical business owner whose sales grew strongly in 2026. Her profit and loss report shows that payroll, materials and advertising grew almost as fast, so profit barely moved. Income tax is generally calculated on profit rather than on sales, and the cash in the bank follows its own timing, so sales alone say little about either one.
Checking profit is the first step of a year-end tax checklist, so pull your own profit and loss report for the year so far and compare it with last year’s. If profit is far from what you expected, that changes how much you may owe, how much you should have paid in estimated tax and which purchases make sense, so it is worth knowing before December 31. For more on measuring profit, see our article on real profit.
Do your bank and your books match?
Reconciliation, a core item on any year-end tax checklist, means matching every transaction in your bank and card statements with what is recorded in your bookkeeping. It catches missing deposits, duplicate entries and expenses filed under the wrong category, and it is much easier to fix in December, while the transactions are recent, than months later. Ask whoever keeps your books whether anything is still unreconciled.
Are business and personal expenses separated?
If personal purchases went through a business account, or business purchases went through a personal one, record them correctly now so your year-end tax checklist starts from clean books. Mixed transactions make it harder to tell which expenses belong to the business, and an expense you cannot document may be difficult to support later.
Where do estimated taxes fit on your year-end tax checklist, and what about January 15?
Estimated tax is how income without withholding gets paid during the year. Individuals, including sole proprietors, partners and S corporation shareholders, generally need to pay it when they expect to owe $1,000 or more at filing, while corporations follow a different threshold. You generally avoid an underpayment penalty by paying at least 90% of this year’s tax or 100% of last year’s, whichever is smaller. If your adjusted gross income last year was above $150,000 ($75,000 if married filing separately), the prior-year figure becomes 110%.
December is a good moment to add this step to your year-end tax checklist by comparing what you have paid with your real 2026 income instead of last year’s. The fourth payment for 2026 is due January 15, 2027, and you do not have to make it if you file your 2026 return by February 1, 2027 and pay the full balance with it. The IRS can charge a penalty for underpaying estimated tax, and it charges interest on penalties, so it pays to check before the date passes. Whether you need to pay estimated tax at all, and how much, depends on your entity type, your income and what has already been withheld.
Do your contractors have a W-9 on file?
Collecting W-9s is one of the simplest items on a year-end tax checklist. If you pay independent contractors, ask each one for a Form W-9 before January. It gives you the name, address and taxpayer identification number you need for the 1099. For payments made in 2026, the reporting threshold for Form 1099-NEC is $2,000, up from $600. Forms for 2025 payments, filed earlier this year, still followed the $600 threshold.
Put the deadline on your year-end tax checklist too, since the forms for 2026 payments are due January 31, 2027. That date falls on a Sunday, so the IRS weekend rule moves the deadline to Monday, February 1, 2027. Which payments need a 1099 depends on who you paid and how, so confirm any doubtful case with your tax advisor.
What changed for equipment and large purchases?
The 2025 tax law, which the IRS now calls the Working Families Tax Cuts and the press calls the One Big Beautiful Bill, changed two rules that matter for purchases. Section 179 expensing now allows up to $2.5 million of qualifying property to be deducted in the first year, reduced when purchases exceed $4 million, and indexed for inflation starting in 2026. Separately, a 100% first-year bonus depreciation deduction is permanent for qualified property acquired after January 19, 2025.
Equipment deserves a place on any year-end tax checklist because both rules apply to property placed in service, meaning ready and in use, so equipment bought in December but not installed or used by December 31 may not count for 2026. Our view is that a purchase should make sense on its own, since a deduction offsets only part of what you spent. Whether a specific purchase qualifies, and how it fits your situation, depends on details that need an individual look.
Which documents belong on your year-end tax checklist?
These eight documents make up the usual year-end tax checklist for records, and gathering them in December keeps the start of the year calm:
- Bank and credit card statements. All 12 months, for every business account and card. December’s statement arrives in early January.
- Bookkeeping reports. The profit and loss report and the balance sheet for the full year.
- Contractor information. A W-9 for every contractor you paid $2,000 or more in 2026, plus the total paid to each one.
- Payroll reports. The year-end payroll summary and the quarterly reports (Form 941).
- Estimated tax payments. The date and amount of each 2026 payment, including the one due January 15.
- Large purchases. Receipts for equipment, vehicles and other big business purchases.
- Loan and lease statements. Interest paid on business loans and credit lines, plus payments on vehicle or equipment leases.
- Letters from the IRS or the state. Any notice you received this year, even one you believe is already resolved.
The IRS retention periods vary by situation, from 3 years in general to at least 4 years for employment tax records, 6 years when income is underreported by more than 25% of the gross income on your return, and 7 years for a worthless securities or bad debt claim. Property records stay until the limitation period ends for the year you dispose of the property. Our article on making better use of your tax records shows how to keep them organized.
When is it worth talking to your tax advisor before December 31?
Some items on a year-end tax checklist depend on your situation more than on a general rule, such as a large purchase, a new hire, a change in how the business is structured, or a year in which income changed a lot compared with the last one. The same goes for estimated payments you are unsure about and for any notice you received. A conversation before December 31 lets those choices be made while they can still count for 2026, and its goal is to pay what is due, with planning, and to see the 2026 result before it is final.
If you would like a second look at your year-end tax checklist before the year closes, the ACP team can help. Fill out the form so we can understand your business and guide you through the next step.
👉🏻 Contact the ACP team
Compliance Note
This article is for general educational purposes only and does not constitute legal or tax advice. Every business is different, and the appropriate approach depends on your specific circumstances. Consult a qualified professional before making financial, legal, or tax decisions.